
Insurance, and specifically the topic of “travel insurance”, has long been a subject I wanted to systematically analyze and organize into a dedicated series.
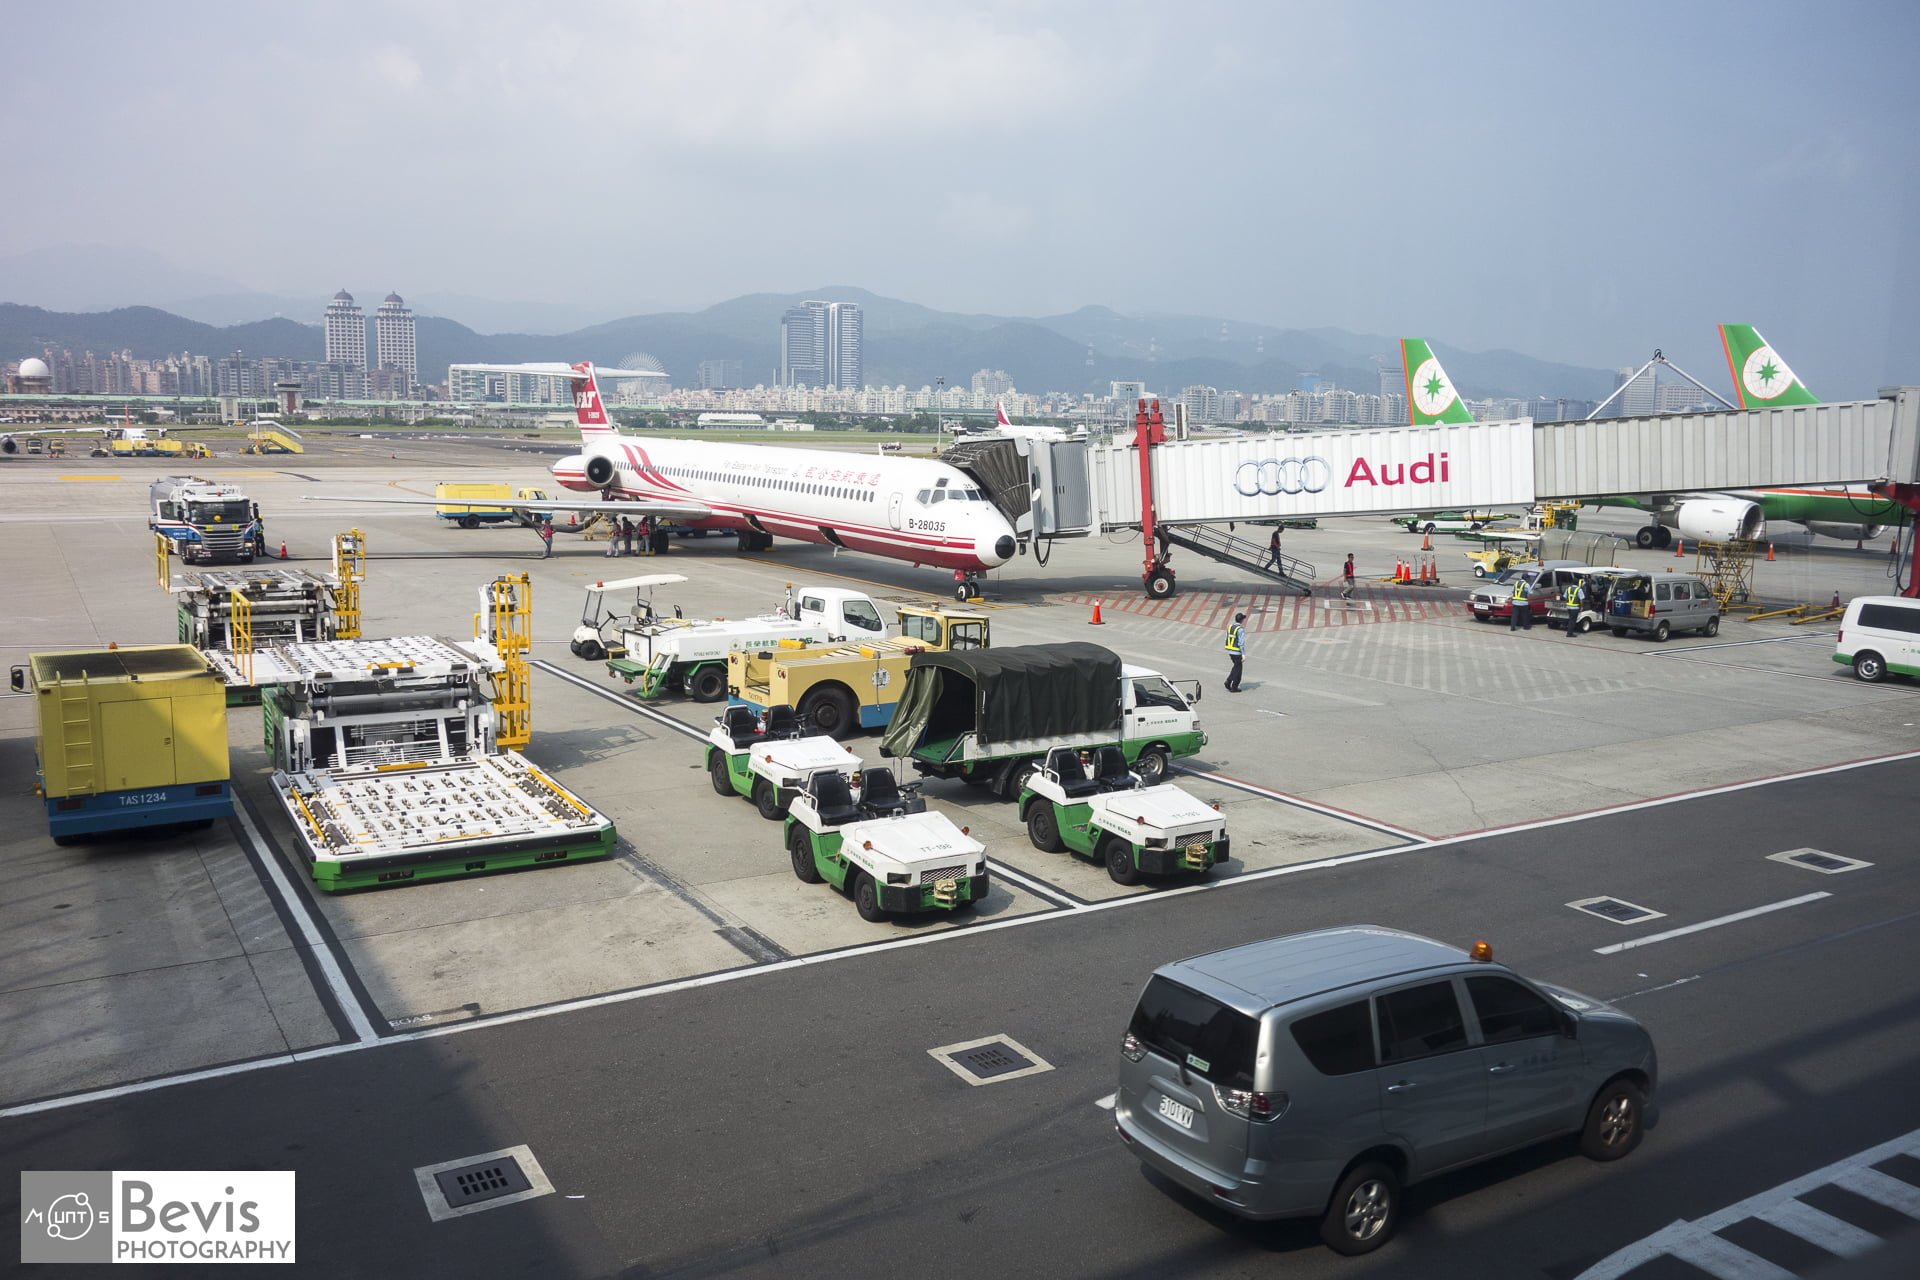
In light of the public shock and attention sparked by the TransAsia Airways crash, let us take an in-depth look at certain “peculiar” institutional blind spots and legal nuances within travel insurance. As for an exhaustive encyclopedia of detailed policy clauses, I will continue my best efforts to procrastinate indefinitely (dodging flying kicks from the editorial team).
Frequent readers of Vedfolnir know that we have sparred several times with various insurers in the past (which makes me sound like an insurance fraudster, though I have always simply stood firmly on legal grounds and contractual terms to advocate for legitimate rights).
In fact, there is an unpublished story involving Nan Shan Life stored away in my drafts waiting for the right moment. That incident prompted me to file a direct complaint with the Insurance Bureau of the Financial Supervisory Commission (FSC)—not over ambiguous clauses or legal grey areas, but because they had unleashed “one rogue” agent whose professional conduct was utterly appalling.
Whenever a major aviation tragedy occurs, beyond praying for survivors and scrutinizing air safety protocols, the most practical and grim issue is ensuring ongoing family livelihoods and fulfilling post-disaster insurance compensation. Many people only realize in the aftermath of a crisis that the policies they thought offered comprehensive coverage actually come with severe restrictions when it matters most.
Fatal Blind Spot 1: Complimentary Credit Card Flight Insurance Is Often a Beautiful Illusion
When advising on travel insurance, the response I hear most often from travelers is: “I always buy plane tickets with my credit card. Banks advertise that charging full airfare grants complimentary coverage worth NT$20–30 million in travel accident insurance! Why would I waste money buying an additional private policy?”
This is without doubt the most widespread and perilous misconception among modern travelers!
The vast majority of complimentary credit card insurance policies are strictly “Public Conveyance Accidental Death & Dismemberment Insurance”!
Pay close attention to the strict legal definition:
- Severely Restricted Coverage Window: It “only covers the duration you are aboard a public transport vehicle” (e.g., from aircraft takeoff to landing, or while riding licensed, scheduled public transit shuttles). Once you roll your luggage past airport terminal doors, if you take a local taxi, rent a car, slip and fracture a bone walking down the street, or get robbed, the payout from this credit card policy is strictly “zero dollars”!
- Total Lack of Overseas Medical and Emergency Evacuation: Complimentary credit card insurance typically only covers accidental death and disability. The overwhelming majority exclude (or cap at negligible amounts) “overseas sudden illness outpatient and inpatient medical coverage”. In regions like North America, Europe, or Japan, where a single emergency room visit costs tens of thousands of NT dollars and an ambulance ride runs several thousand US dollars, such complimentary policies offer zero real protection.
In other words, credit card travel insurance is designed solely to cover extreme aviation disasters while in transit. It is fundamentally not a comprehensive “door-to-door full-trip travel policy”.
Fatal Blind Spot 2: Confusing “Travel Accident Insurance” with “Travel Inconvenience Insurance”
Many travelers purchase policies casually at airport kiosks, assuming a single policy covers every possible calamity. In reality, travel insurance on the market is bifurcated into two core systems:
| Insurance Type | Core Protection Objective | Primary Claim Coverage | Incident Example |
|---|---|---|---|
| Travel Accident Insurance (Personal Safety) | Insures “life, health, and physical safety” | Accidental death, permanent disability, major burns, sudden overseas medical emergencies, medical evacuation | Plane crash, traffic collision fracture while traveling, emergency appendectomy abroad |
| Travel Inconvenience Insurance | Insures “itinerary continuity and personal property” | Flight delays (usually 4+ hours), baggage delays/loss, trip cancellation/interruption, passport replacement costs | Typhoon grounding flights at transit hubs, airline misplacing checked baggage |
Tragedies such as plane crashes involve catastrophic casualties, which trigger the massive lump-sum death benefit of “travel accident insurance”. On the other hand, if a budget airline suffers mechanical problems resulting in half-day delays, or if luggage fails to make a connection, that triggers “travel inconvenience insurance” meal and lodging stipends.
Their natures are completely distinct. When embarking on independent travel, “combining both coverages” is essential—never sacrifice one for the other.
How Do Multiple Layers of Protection Overlap During a Major Aviation Disaster?
If a catastrophic aviation disaster unfortunately occurs, the legal tiers of claim rights available to the victim’s family are constructed from several overlapping defense lines:
- Statutory Airline Liability Insurance: Under the Civil Aviation Act of the Republic of China (ROC) and international conventions (such as the Montreal Convention), airlines are mandated to maintain third-party liability and passenger liability insurance. This payout is borne by the carrier’s insurer, covering statutory death compensation and emotional distress damages (often exceeding NT$10 million per victim).
- Credit Card Public Transit Accidental Death Insurance: If ticket fares were paid in full using an eligible credit card, cardholders can claim accidental public conveyance death benefits under the bank’s collective policy with its property insurer.
- Privately Purchased Commercial Travel Accident Insurance: Commercial travel accident insurance policies taken out individually with life or non-life insurance companies prior to departure.
- Regular Personal Life and Personal Accident Policies: Whole life, term life, and personal accidental death policies held by the insured individual in their everyday life.
Crucial Legal Insight: Under ROC insurance jurisprudence in Taiwan, with the exception of indemnity-based actual expense medical policies that may restrict duplicate original receipts, all accidental death and life insurance benefits operate as agreed-value fixed compensation, meaning benefits from multiple separate policies can legally be claimed simultaneously and paid in full without offset!
This is precisely why maintaining adequate personal coverage both regularly and prior to traveling abroad constitutes the ultimate economic safeguard for loved ones in worst-case scenarios.
Smart Buyer’s Practical Guide: Three Core Rules for Self-Protection
When purchasing commercial travel insurance before departure, always keep these three golden rules in mind:
- Coverage timeline must be strictly “door-to-door”: Never set policy effective dates to just flight takeoff and landing times! Ensure coverage begins the exact minute you walk out your front door and lasts until you step back into your living room upon return. Ground transit to and from the airport by taxi, high-speed rail, or bus falls squarely within travel accident insurance coverage.
- Always attach “overseas sudden illness medical insurance” and “overseas emergency assistance”: Verify specifically whether the policy includes “emergency air ambulance repatriation” and that the emergency assistance limit is sufficient (recommended at least US$50,000 to US$100,000 or more).
- Preserve all original receipts, invoices, and boarding pass stubs: Whether claiming flight delay stipends under inconvenience insurance or reimbursing overseas medical bills, all flight delay certifications, boarding stubs, original medical diagnostic certificates, and itemized billing statements must be meticulously preserved.
Related Reading:
Conclusion: The Essence of Insurance Is Not Profit, but Love and Responsibility
With every exciting journey, we embark with hopes of returning home safely.
Yet truly mature travelers understand that before savoring beautiful destinations, they must establish solid safeguards to shield themselves and their closest family.
Mastering insurance policies is not about chasing windfall payouts; it is about ensuring that if an unforeseen storm strikes, our loved ones will not have to endure devastating financial ruin on top of heartbreak. By examining contracts clearly and securing thorough coverage, we can take to the skies with genuine peace of mind.
Support Independent Perspectives & In-Depth Insights
Every thoughtful analysis and candid critique comes from our dedication to truth and quality. We choose not to follow sensational algorithms or clickbait headlines.
Sustaining independent research requires reader support. Make a one-time or monthly contribution, securely processed by Google.
Payments secured by Google · Manage or cancel anytime in your Google Account

Comments